

Cashli: Cash Advance & Rewards
Cashli Funds
- 4.2
- 2.75K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
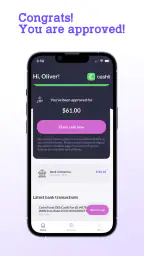
Cashli: Cash Advance & Rewards Pros and Cons
Pros
- Fast application process with clear eligibility requirements
- No traditional credit check is required for many users
- Flexible repayment options can help manage short-term cash needs
- Rewards may provide extra value beyond cash advances
- Useful budgeting tools help track spending and upcoming repayments
Cons
- Advance amounts may be limited for new or infrequent users
- Fees and optional tips can increase the total repayment cost
- Repayment dates may arrive quickly after receiving an advance
- Eligibility and available features can vary by state or location
- Some features may require subscriptions or recurring membership payments
 Analysis by All-app
When an unexpected bill lands between paydays, the most useful financial tool is often the one that helps me understand my options quickly rather than the one with the longest feature list. Cashli: Cash Advance & Rewards is designed for that narrow moment. It is a free finance app from Cashli Funds, aimed at people looking for access to a small cash advance through a phone instead of immediately turning to a bank, credit card, or a more traditional lending service.
I approached it as a decision guide rather than a promise of easy money. The store summary presents the app as a way to get up to 150 bucks now, but that headline should not be treated as a guaranteed outcome for every user. A cash advance is still a financial decision, and the important questions are whether the app suits the urgency of the situation, whether the repayment expectations are comfortable, and whether its process feels more useful than the alternatives already available to you.
What I would check before choosing Cashli
My first decision criterion is the size and timing of the need. This is not the kind of app I would consider for a large purchase, long-term borrowing, or a recurring budget gap. Its appeal is much clearer when the problem is temporary: a grocery shortfall, a transport expense, or a small bill that arrives before income does. If the same shortage appears every month, an advance may only move the pressure forward instead of solving it.
The second criterion is how carefully I can review the terms before accepting anything. With any cash advance app, I would read the amount offered, the repayment date, any applicable charges, and the steps required to receive and repay funds. I would also make sure I understand what happens if I decide not to continue. A quick application is helpful, but speed should never replace a clear look at the commitment.
The third criterion is trust and fit. Cashli has an average rating of 4.2 from around 4.9 thousand ratings, and it has passed the 100 thousand install mark. Those figures suggest that the app has attracted a meaningful audience, but they do not tell me whether it is right for my particular financial situation. Reviews can reveal general satisfaction, while my own circumstances determine whether an advance is sensible.
I would also consider the app’s basic accessibility. It is free to install, carries an Everyone age rating, and supports Android versions from 8.0 onward. That makes it approachable for many Android users, including people who do not have a recent phone. The current version is 1.0.19, so I would still keep the app updated through the official app marketplace and pay attention to the screens shown during the application process.
A realistic payday-gap example
Imagine I have enough money for rent and regular bills, but a necessary prescription and a higher-than-usual electricity payment arrive in the same week. I am not looking for a personal loan that stretches over months; I need to bridge a small gap and know exactly when my next income arrives. In that situation, Cashli could be worth checking because its purpose is closer to short-term relief than to conventional borrowing.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
My workflow would be simple but deliberate. I would open the app, review the available advance information, compare the amount with the actual bill rather than borrowing the maximum, and check the repayment details before proceeding. If I only needed a modest amount, taking less than the displayed limit would reduce the chance of creating a larger deduction later. That is one of the most important practical habits with this type of service: the maximum available is not automatically the appropriate amount.
I would then place the repayment date beside my next pay date and other fixed commitments. If repayment would leave me short for food, housing, utilities, or transport, I would stop and look for another solution. The app may help with timing, but it cannot make an unaffordable repayment affordable. That distinction is easy to miss when the immediate problem feels urgent.
Where Cashli feels most useful
The strongest part of Cashli is its focus. Instead of presenting itself as a full banking replacement, it centers on a small, immediate cash need. That narrow purpose can make the app easier to evaluate than a broad financial platform filled with budgeting, investing, credit monitoring, and account-management tools I may not need at that moment.
I also like the fact that the app includes rewards in its identity. For a user who already wants a cash-advance tool and is willing to explore the rewards side, that combination may feel more engaging than a bare borrowing interface. I would treat rewards as an extra, not as a reason to borrow. A reward should never justify accepting an advance that does not fit my budget.
Another practical strength is the low barrier to trying the app. There is no purchase price to download it, and the Everyone rating makes it suitable for a broad audience from an age-classification perspective. That does not remove the need to review financial terms, but it does mean I can inspect the experience without first paying for access.
Cashli Funds is also easy to identify as the developer, which matters when I am checking that I am using the intended application rather than an imitation. I would still install it only from a trusted official marketplace and verify the developer name before entering personal or financial information. That small check is especially important for money-related apps.
Three habits that make the experience safer
My first tip is to calculate the repayment impact before selecting an amount. I would write down the money expected on the next payday, subtract rent, utilities, food, transport, and existing commitments, and only then consider whether an advance fits. This turns the app from an impulse button into one part of a short budget review.
My second tip is to use the app for a defined event, not as a standing supplement to income. I would name the expense in my notes, such as “car repair” or “medical purchase,” and record the repayment date. If I cannot explain what the money is for or how it will be repaid, I would not proceed. This simple rule helps separate a temporary timing issue from a deeper financial problem.
My third tip is to inspect the full flow before committing. I would look for the amount, timing, repayment method, and any conditions shown in the app, then take a screenshot or note the details for my own records where appropriate. I would not assume that the promotional wording tells me everything important. The actual offer and the final confirmation screen are the parts that should guide my decision.
A fourth useful habit is to keep the rewards feature in its proper place. I would check whether earning or using rewards requires additional activity, but I would not change my spending simply to chase them. Rewards can be pleasant when they fit naturally into my routine; they become counterproductive when they encourage extra purchases or make borrowing feel like a game.
Where the usual alternatives may fit better
Cashli is not automatically better than every other option. If I already have an emergency fund, using a small amount from that fund is usually simpler because there is no new advance application or repayment schedule. The trade-off is that withdrawing from savings reduces my cushion, so I would replenish it afterward rather than treating the withdrawal as free money.
A bank overdraft or an existing line of credit may be more suitable for someone who already understands its terms and has a reliable repayment plan. A credit card can also be more flexible for a purchase, especially if the user is disciplined about paying the balance. However, those products can carry their own costs and tempt people to maintain a balance, so familiarity does not automatically make them cheaper or safer.
For a larger expense, a conventional personal loan may offer a more structured schedule than a short-term advance. It may also involve more paperwork and a slower decision, which is precisely why it is not the natural choice for a small emergency between paydays. I would match the borrowing tool to the duration of the need: brief timing problem, short-term option; substantial or repeated problem, broader financial planning.
Community assistance, an employer advance, a payment extension, or help from someone I trust may be better in some situations. These choices can involve conversations that feel uncomfortable, but they may avoid adding another repayment obligation. I would especially consider them if an advance would leave me short again before the next payday.
This is where Cashli’s category matters. It competes mainly on convenience and immediacy, not on replacing savings, banking, or financial counseling. Someone who wants a complete money-management system should look elsewhere. Someone who needs a focused way to investigate a small cash gap may find its narrower purpose more relevant.
Questions I would answer before installing it
Is the advertised amount guaranteed? I would not assume that it is. The store summary describes access to up to 150 bucks, while the amount available to an individual can depend on the app’s own process and the user’s circumstances. I would treat the displayed offer, not the headline, as the figure that matters.
Does free mean borrowing is free? No. The app itself is free to install, but that does not automatically mean every advance has no cost or condition. Before accepting money, I would review the complete offer inside the app, including any repayment details and charges that apply to that specific transaction.
Can I use it for regular bills every month? I would strongly hesitate. Repeated advances can create a cycle in which the next payday is already partly committed. Cashli makes more sense to me as an occasional bridge for a defined need, not as a substitute for income or a permanent budget category.
Is it suitable for someone with an older Android phone? It supports Android 8.0 and later, so many older compatible devices should be able to run it. I would still keep the operating system and app current, and I would avoid entering sensitive information on a device that is rooted, shared, or poorly secured.
Are the rewards the main reason to choose it? Not in my view. They may add value for someone who already likes the app’s core service, but the advance terms should be the deciding factor. If the borrowing arrangement does not fit my finances, rewards would not change that conclusion.
The switching cost people often overlook
Moving from a familiar bank or card to a cash-advance app has a cost beyond downloading another application. I would need to learn a new interface, understand a new repayment process, monitor another financial account, and remember another deadline. That mental overhead is small for a one-off emergency, but it becomes significant if I use several money apps at once.
There is also a record-keeping cost. I would want to save confirmation details, watch my bank activity, and make sure the repayment does not collide with essential bills. If I later stop using Cashli, I would review any pending obligation before deleting the app. Removing an icon from my phone is not the same as closing out a financial commitment.
For that reason, I would not install it casually just because the download is free. I would install it when I have a clear use case and enough time to read the offer. If my need is not urgent, comparing savings, a payment extension, and existing credit first may produce a better result with less administrative work.
My recommendation after weighing the trade-offs
I would recommend Cashli to an Android user who needs to investigate a relatively small, short-lived cash gap, understands that “up to” is not a promise, and can repay comfortably on the stated schedule. Its free entry point, focused purpose, rewards angle, and broad device compatibility make it worth considering in that specific situation. The app has also built a visible user base, with around 2.7 thousand written reviews alongside its overall rating, so it is not an unknown download with no public reaction.
I would not recommend it to someone who is already borrowing to cover essentials every pay period, cannot identify a reliable repayment source, or wants a full banking and budgeting replacement. In those cases, savings, a negotiated bill extension, employer support, community assistance, or professional financial guidance may be more appropriate. A short-term advance can relieve pressure today while increasing it later, and no rewards feature changes that basic trade-off.
My final view is cautiously positive. Cashli: Cash Advance & Rewards is most convincing when I treat it as a narrow tool for a clearly defined timing problem, not as extra income. I would compare the actual offer with my existing options, borrow only what the expense requires, record the repayment date, and keep the rewards secondary. Used with that discipline, Cashli is a practical option to investigate, but not a replacement for an emergency fund or a sustainable budget.
Frequently Asked Questions
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app designed to help eligible users access potential cash advances and earn rewards through selected activities. After creating an account, you may be asked to provide personal and financial information for identity verification and eligibility checks. Available services, advance amounts, repayment terms, and rewards can vary depending on your location, profile, and the app’s current policies.
Is Cashli a legitimate and safe app to use?
Before using Cashli, download it only from an official app store and review the developer information, privacy policy, user agreement, and permissions requested. The app may handle sensitive data, including identity and financial details, so users should understand how information is collected, stored, and shared. No financial app can guarantee complete protection from fraud, so use strong login credentials and avoid sharing verification codes.
How much money can I receive through Cashli, and are there fees?
The amount you may be offered through Cashli is not necessarily the same for every user. Eligibility, income information, account history, location, and other verification factors can affect available offers. Depending on the product shown in the app, fees, expedited-transfer charges, subscription costs, or other expenses may apply. Carefully check the final disclosure, total repayment amount, due date, and annualized cost before accepting anything.
When do I have to repay a Cashli advance?
Repayment details depend on the specific offer presented to you and the agreement you accept. The app should display the repayment date, payment amount, and any applicable fees before confirmation. Make sure your linked payment method has sufficient funds on the scheduled date, because a failed payment could lead to additional charges, account restrictions, or other consequences. Contact Cashli support promptly if you anticipate difficulty repaying.
How do Cashli rewards work, and can I withdraw them as cash?
Cashli rewards may be earned by completing qualifying actions, participating in promotions, or meeting requirements described inside the app. Reward availability, expiration dates, minimum withdrawal thresholds, and eligible redemption methods can change over time. Not every reward is necessarily convertible to cash, and some offers may include exclusions or verification requirements. Read the individual promotion terms carefully before spending time or submitting personal information.


